Third party only
The legal minimum. Covers injury to other people and damage to their property, and nothing for your own vehicles.
FleetQuote
One enquiry for the whole fleet, whether that is two vans or twenty lorries, with prices back from several specialist providers.
Partnered with Quotezone
What being partnered with Quotezone means FleetQuote is a trading name of Simply Quote Comparison Ltd. Enquiries are passed to Quotezone, a trading style of Seopa Ltd (FCA FRN: 313860), which operates the quote panel. Simply Quote Comparison Ltd is an Introducer Appointed Representative of Seopa Ltd (FCA reference: 1011184), so we may be paid a commission if your enquiry leads to a policy. We do not give advice or make recommendations. Your choice of provider is entirely your own.FleetQuote is a quotation service, not an insurer or broker.









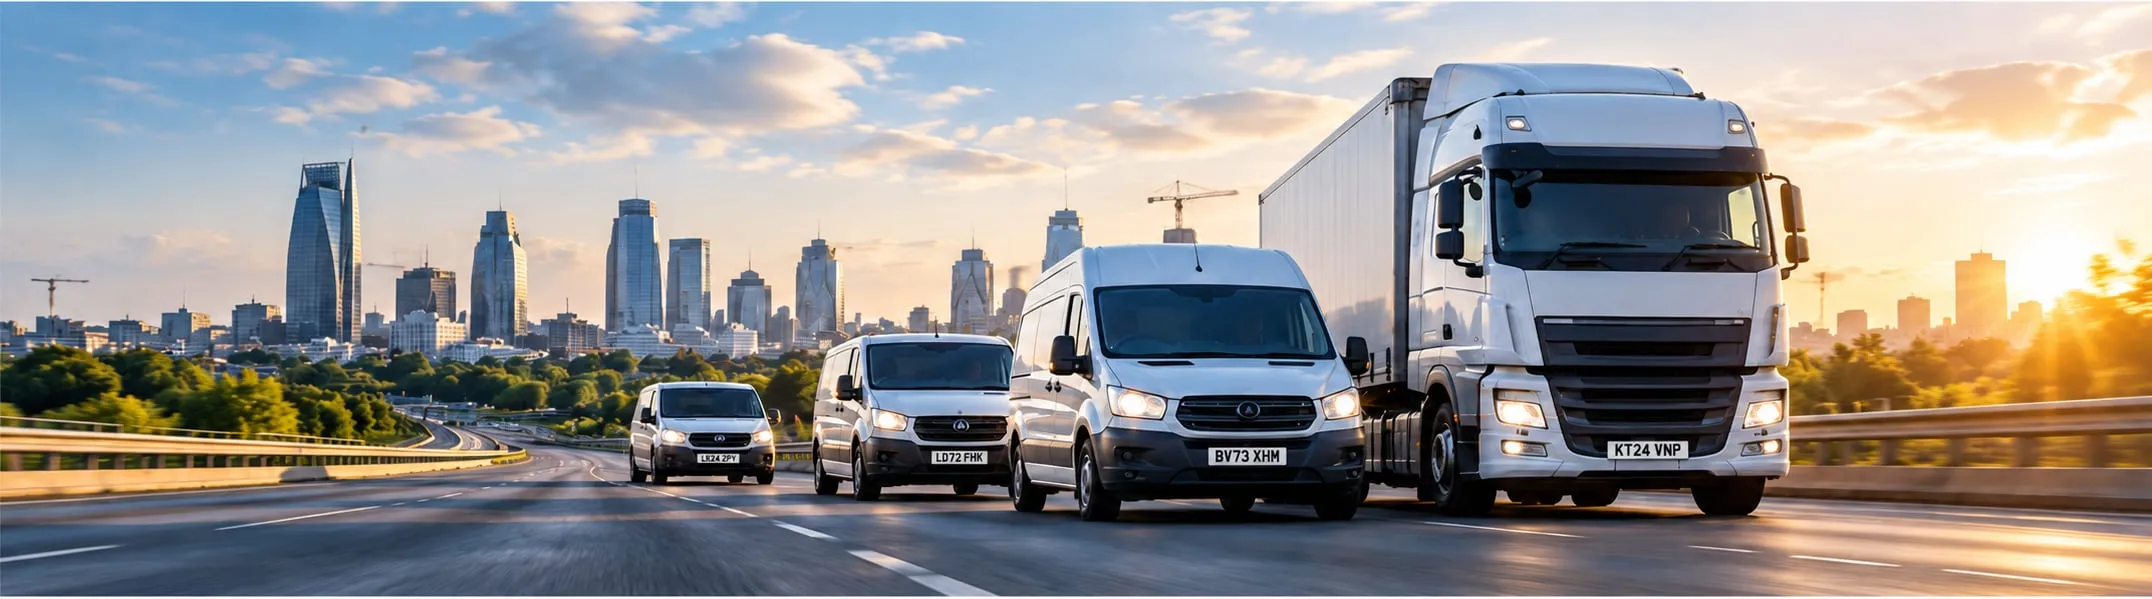
A pair of trade vans, a mixed yard of cars and tippers, or a haulage fleet. Pick the closest match to see what insurers ask about it.
One set of questions, answered once. It takes about two minutes, and nothing is committed at the end of it.
Questions about your vehicles, business, current cover and drivers. It takes about two minutes and you don’t need registration numbers yet.
Your enquiry goes to Quotezone, an insurance quote panel authorised by the Financial Conduct Authority, which puts it to brokers that arrange cover for fleets.
A broker contacts you to go through your requirements, ask for any further detail and provide quotes. You decide whether to go ahead.
Fleet insurance explained
Fleet insurance is one motor policy covering several vehicles run by the same business, with one renewal date, one vehicle schedule and one set of driver rules.
It is written on the same three cover levels as any motor policy, with the extras that working fleets need priced separately on top.
The legal minimum. Covers injury to other people and damage to their property, and nothing for your own vehicles.
Adds cover for your own vehicle if it is stolen or damaged by fire, but still nothing for accidental damage to it.
Adds accidental damage to your own vehicles whoever is at fault. Most working fleets sit here, and some policies mix levels by vehicle.
Available on most fleet policies, priced separately, and worth deciding on deliberately rather than accepting whatever last year's renewal happened to include.
Covers what you carry. Check the limit per vehicle and per load, and whether customers’ goods are included.
Covers tools and equipment kept in vans. Read the overnight and forced-entry conditions before you rely on it.
Ask whether recovery takes a laden vehicle to your depot or only to the nearest garage.
Helps recover uninsured losses after a non-fault accident, such as your excess, hire costs and lost earnings.
Check how many days are included and whether it is full cover or the legal minimum while abroad.
A standard courtesy car is little use if you lose a 3.5 tonne van, so ask what is actually provided.
The wrong class of use is the common mistake. A van carrying your own tools is carriage of own goods. A van delivering customers' parcels for payment is hire and reward. Insure the wrong one and a claim can be refused, so describe the work as it actually happens. Our guide to vehicle class of use sets out each class with examples.
Fleet size
There is no legal minimum. Insurers set their own thresholds, and many will consider a fleet policy from two or three vehicles.
What usually matters more than the count is how the vehicles are used, who drives them and what your claims record looks like. A business with three vans on multi-drop delivery work is a different risk from one with three cars used by directors, even though both have three vehicles.
As a general pattern in the market, small or mini fleet products start at two or three vehicles and run up to somewhere around 12 to 20, after which policies are usually rated as a full fleet on the business's own claims experience. Thresholds vary by insurer, so the only way to know is to ask with your actual vehicle list in front of you.
2+
Vehicles many insurers will consider
12–20
Where mini fleet products usually top out
3–5 yrs
Claims experience insurers typically ask for
What the law requires
Every vehicle used on a road or other public place needs at least third-party insurance. The other duties below are the ones insurers ask about, because they shape the risk.
| Duty | What it means in practice |
|---|---|
| Insure every vehicle | At least third-party cover for any vehicle used on a road or other public place, under the Road Traffic Act 1988. Road Traffic Act 1988, s.143 |
| Keep it insured, or declare it off road | A registered keeper must keep a vehicle insured unless it has a SORN. An uninsured vehicle can mean a £100 fine, and it can be clamped, impounded or destroyed. GOV.UK: uninsured vehicles |
| Show every vehicle on the MID | Police check the Motor Insurance Database, including through number plate cameras. Add vehicles as they join the fleet, hire vehicles included, and remove them when they leave. askMID |
| Hold an operator licence over 3.5 tonnes | In Great Britain you generally need a goods vehicle operator’s licence to use vehicles over 3.5 tonnes for business, including carrying your own goods. GOV.UK: goods vehicle operators |
| Check your drivers’ licences | A driver can share their record through GOV.UK, which creates a check code valid for 21 days. Larger fleets use DVLA’s Access to Driver Data service with each driver’s consent. GOV.UK: view or share a driving licence |
What it costs
There is no reliable UK-wide average, because a three-van plumbing firm and a twenty-lorry haulier are priced on completely different models. What a fleet costs comes down to the rating factors below.
Fleet premiums are built from the vehicles, the drivers and your claims record rather than from a list price. Each insurer weighs these on its own model, which is why the same fleet can come back at very different numbers.
| Rating factor | Effect on the premium |
|---|---|
| Fleet size and vehicle mix | Values, gross weights and the share of cars, vans and HGVs all move the price |
| Class of use | Own goods, hire and reward and private use are rated differently, and getting it wrong voids cover |
| Claims experience | The fleet’s record over three to five years usually matters more than any single claim |
| Driver profile | Ages, licence history and convictions, or your vetting process on any-driver policies |
| Overnight parking | A locked compound, a driveway and a city street are three different theft risks |
| Where you operate | Urban multi-drop, long motorway runs and regular London work have different claims patterns |
| Telematics and cameras | Some insurers take tracking and dashcam evidence into account at renewal |
| Excess and cover level | A higher voluntary excess lowers the premium, and add-ons are priced on top |
Our guide to what a fleet policy costs goes through each factor, and reducing the premium covers the levers that make a difference over time.
By industry
A scaffolder's flatbeds, a care provider's pool cars and a courier's multi-drop vans raise different questions at quote. These pages set out what insurers ask each trade.
See all industriesGuides
Practical guidance on cover, claims and renewals, with the sources listed and a review date on every page.
View all guides What is fleet insurance? Fleet insurance puts several business vehicles on one motor policy. This guide explains how that works in practice, how it differs from individual policies, the terms you will hear from brokers and insurers, and what a fleet policy does not cover. Read guide
 How many vehicles do you need for fleet insurance? The law does not set a minimum number of vehicles for a fleet policy. Insurers set their own thresholds, and those vary. This guide explains how small fleets are treated, when one policy starts to beat several, and the edge cases worth knowing about. Read guide
 How much does fleet insurance cost? You will not find a trustworthy average price for fleet insurance, and this guide explains why. Instead it sets out how insurers build a fleet premium, which rating factors carry weight at your fleet size, how tax and mid-term changes affect the bill, and why similar fleets get different quotes. Read guide
Questions
No. FleetQuote is an introduction service. We collect details of your fleet and pass your enquiry to Quotezone, which operates a panel of insurance brokers and insurers. A broker discusses your requirements, provides any quotes and arranges the policy if you go ahead. We don’t give advice or sell insurance ourselves.
There is no legal minimum. Each insurer sets its own threshold, and some will consider fleets as small as two or three vehicles while others want more. If you run two or more business vehicles, it’s worth asking. Our guide to minimum fleet sizes explains how smaller fleets are usually handled.
No. Sending an enquiry is free and you are under no obligation to take out a policy. FleetQuote is paid a commission if your enquiry leads to a policy. Any premium, fees or terms for a policy will be explained to you by the broker before you decide.
We pass your details to Quotezone, which puts your enquiry to the fleet brokers on its panel. One of them will contact you using the phone number or email address you give us, and will usually ask for more detail, such as vehicle registrations, driver information and your claims experience, before presenting quotes.
For the enquiry itself, rough figures are fine: how many vehicles and drivers, the types of vehicle, when your renewal is and whether you have had claims. For quotes, the broker will typically ask for a vehicle schedule, driver details and claims experience from your current insurer.
Many fleet policies can include a mix of vehicle types, each rated for its own use, although not every insurer covers every class of vehicle. List everything you run in the form and the broker will look for cover that fits the whole fleet.
We share your enquiry with Quotezone and the brokers on its panel so they can respond to it. We don’t sell your details to other companies. Marketing emails from FleetQuote are a separate, optional choice on the form. Our privacy policy explains how your information is handled.
Last reviewed
General information about UK fleet insurance, not advice. How we write and check our content
Ready to get started?
Answer the questions once and a specialist provider will be in touch.
Takes around 2 minutes
One enquiry for the whole fleet, with prices back from several specialists.